OPEC+ officially concluded a phase of production cuts, which includes a reduction of 1.6 million barrels per day, in September 2023. This production cut was first agreed upon earlier this year and aims to manage the global oil market. However, another layer of production cuts, amounting to 2 million barrels per day, will continue until the end of 2026. These increased production ceilings initially appear to indicate market management by OPEC+, but reality shows that these ceilings are currently of little effect.
Gulf Producers and Existing Challenges
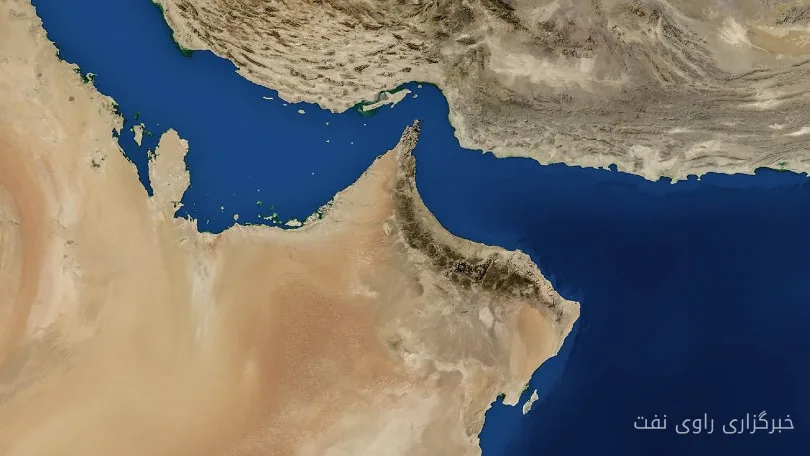
Gulf producers, especially Saudi Arabia and other OPEC members, have been consistently producing below their designated quotas for months due to disruptions caused by the war with Iran. Now that these countries' exports are gradually returning to normal, the majority of them have still not reached their allowed production ceiling. This situation means that any changes to the production ceiling will have little impact on the market. For this reason, the market's reaction to OPEC+'s recent decisions, particularly regarding the December ceiling, has been very limited.
Read more: Qatar Condemns Attack on LNG Carrier
Incentives and Consequences
Currently, the incentives for Saudi Arabia and other Gulf producers are aligned with maintaining exports without political pressure and criticism regarding quota violations. This allows them to effectively engage with the oil market. On the other hand, Russia also benefits from stable prices and, given the existing challenges in transportation and Western sanctions, seeks to maintain its export profit margins. Any official increase in supply could lead to price reductions and further pressure on the current situation.
For consumers, the lack of fresh supply is not currently bad news, although the return of Gulf exports could reduce price pressure in the future.
OPEC+ currently needs to review the production capacity of its members in the fourth quarter of this year. The result of this review will form the basis for determining quotas in 2027. Each country has an incentive to show higher production capacity, as a larger number means a bigger share in the market.
Overall, there are three likely narratives regarding the future situation. First, the "Stasis Until New Year" scenario, where ceilings are expected to remain unchanged, provided that Gulf exports return without disruption. The second narrative is the "Baseline Struggle," where members may push for a larger market share, which could lead to tensions within the group. Finally, the third narrative is the "New Shock," which involves an escalation of the war with Iran or disruptions in exports, potentially leading to sudden price changes.
One less visible consequence is that as the market becomes accustomed to the ineffectiveness of ceilings, OPEC+'s credibility as a supply manager diminishes. In the future, if this group genuinely wants to reduce or increase production, the market may not take this message seriously. Ultimately, the question arises whether OPEC+ is still capable of managing the market or if it is merely waiting for wars to dictate the supply path for it.
Read more: OPEC+ Oil Production Targets Remain Steady for December · Oil on the Verge of Fourth Monthly Price Increase