LR Tankers has closely examined the status of naphtha transportation in a recent report, emphasizing that changes in freight rates have had a major impact on the naphtha market. Specifically, in October, the freight rate for LR2 from the Mediterranean to Japan averaged around $65 per ton, fluctuating between $45 and $120 per ton. These fluctuations are clearly higher than the range of $20 to $45 per ton observed for most of 2025.
Rising Transportation Costs and Their Impact on Naphtha Transfers
Freight rates for LR2 from the Mediterranean to Japan in October have decreased by 25 percent from the mid-October peak, but they are still significantly higher than the average naphtha rate. This situation indicates that although the naphtha market has been challenged by fluctuations in freight rates, shipments are still being moved, albeit in smaller quantities and using smaller vessels.
Read more: Technical disruption at Abadan oil refinery causes increased smoke in the sky
In October, two LR2 vessels carried naphtha only 2 times out of 24 shipments of West naphtha, down from 6 times in January. In contrast, MR shipments increased from 10 to 21 times. This change has mainly occurred in the Mediterranean, which sent 15 MR shipments to Asia in October, while only one was sent to Asia in January. Meanwhile, two shipments have been sent from the Gulf of America.
Changes in the Naphtha Market and Future Outlook
Access to LR2 vessels has been limited due to heavy activity in the region. More LR2 vessels are located in the east than in the west, and most are operating on clean routes from the Middle East and India. Eastern naphtha has increasingly relied on LR1 and MR vessels. In October, MR vessels carried 22 shipments of Middle Eastern naphtha, up from 15 shipments in January, while LR2 shipments decreased from 31 to 10.
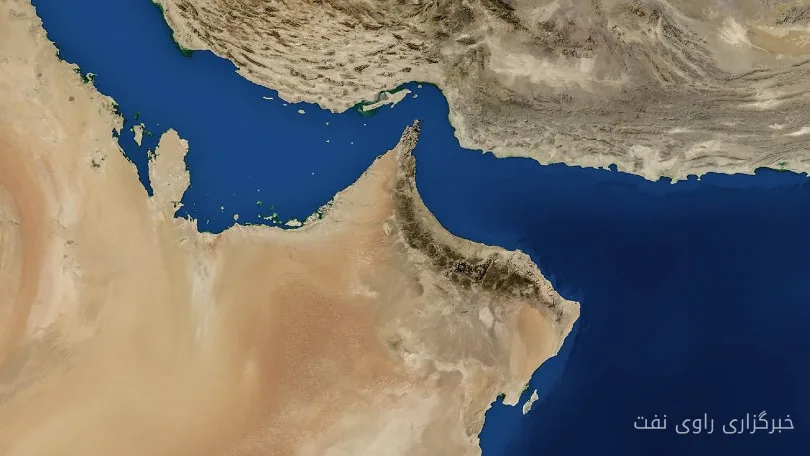
Freight rates for LR1 and LR2 from the Persian Gulf to Japan have more than doubled since July, and rates for LR1 and MR from the western coasts of India to Japan have also more than doubled since August. Attacks on tankers, traffic in the Gulf of Oman, and limited LR vessel listings have made conditions difficult for any route to Asia. However, LR rates from the Persian Gulf have slightly decreased in the last week of October.
Ultimately, despite improving raw material economic conditions, cracker margins remain thin. In October, the price gap between ethylene and naphtha fell below the 2025 average, and ethylene prices failed to keep pace with rising naphtha prices. While weakness in downstream petrochemical margins and ongoing revisions in crackers continue to impose constraints on demand, it is expected that if LR rates continue to decline and approach price gaps, more Western naphtha shipments will return in December loadings.
Read more: OPEC+ production targets for December remain unchanged · TAPICO Holding unveils 5 important news from the country's oil and petrochemical industry