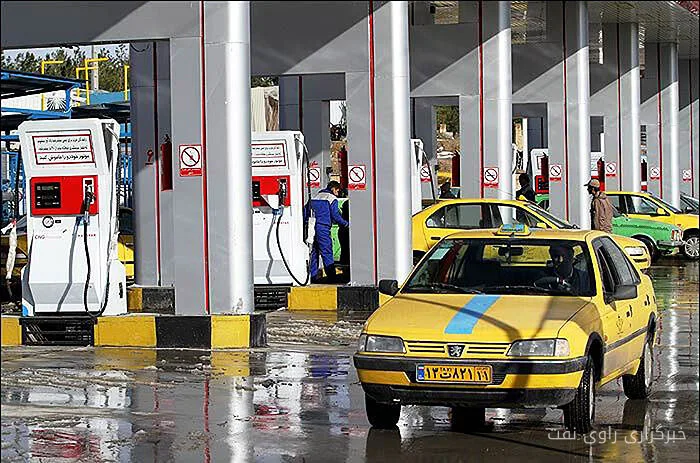
The U.S. diesel export ban could have serious implications for global mining operations, particularly in Latin America. The United States, as the largest diesel exporter in the world, is considering restrictions on the export of this fuel to reduce domestic diesel prices, which have risen due to current conflicts with Iran and damage to diesel production facilities in Russia.
Latin American Countries' Dependence on U.S. Diesel
Latin America is generally dependent on imports from the United States to cover about one-third of its diesel needs. According to a report by S&P Global Energy Horizons on September 22, countries like Chile, Peru, Mexico, and Brazil, which are key producers of metals such as copper, silver, lithium, and iron ore, are heavily reliant on U.S. diesel.
Read more: Analysis of the Reduction and Replacement of Iron Ore Reserves by Wood Mackenzie
Analysts emphasized that sensitivity to diesel prices in Latin America is particularly high in Mexico. In April 2026, diesel inventories in Mexico fell to less than six days of supply. While Chile is 88% dependent on U.S. diesel imports, this situation could severely impact metal production and prices in the country.
Economic Consequences for the Mining Industry
The diesel export ban could lead to increased metal prices and costs for producers. According to the S&P Global Energy Horizons report, diesel accounts for nearly 6.5% of the operating costs of large-scale copper mines in Chile in 2025. With average prices for imported diesel expected to rise by 41% in 2026 compared to 2025, concerns about fuel costs for this sector have increased.
Analysts believe that if this ban continues, the risk of local shortages in Latin American countries will rise due to increasing costs and declining inventories. This could directly affect metal prices and lead to reduced economic performance in these regions.
Especially in Mexico, President Claudia Sheinbaum has announced that the government may continue supportive measures to maintain the diesel price cap, which is set at 27 pesos per liter ($1.56 per liter), until the end of this year.
Currently, the five main export markets for U.S. diesel and related fuels include Mexico, Chile, Brazil, the Netherlands, and Ecuador, which together account for 53.2% of U.S. diesel exports in 2025. Total U.S. exports in this category are expected to reach 418.1 million barrels in 2025.
Read more: Improving Seafarers' Welfare with Participation from Over 1000 Companies in CWSA · Analysis of the Effects of the Diesel Export Ban by the Trump Administration on the U.S. Fuel Market